

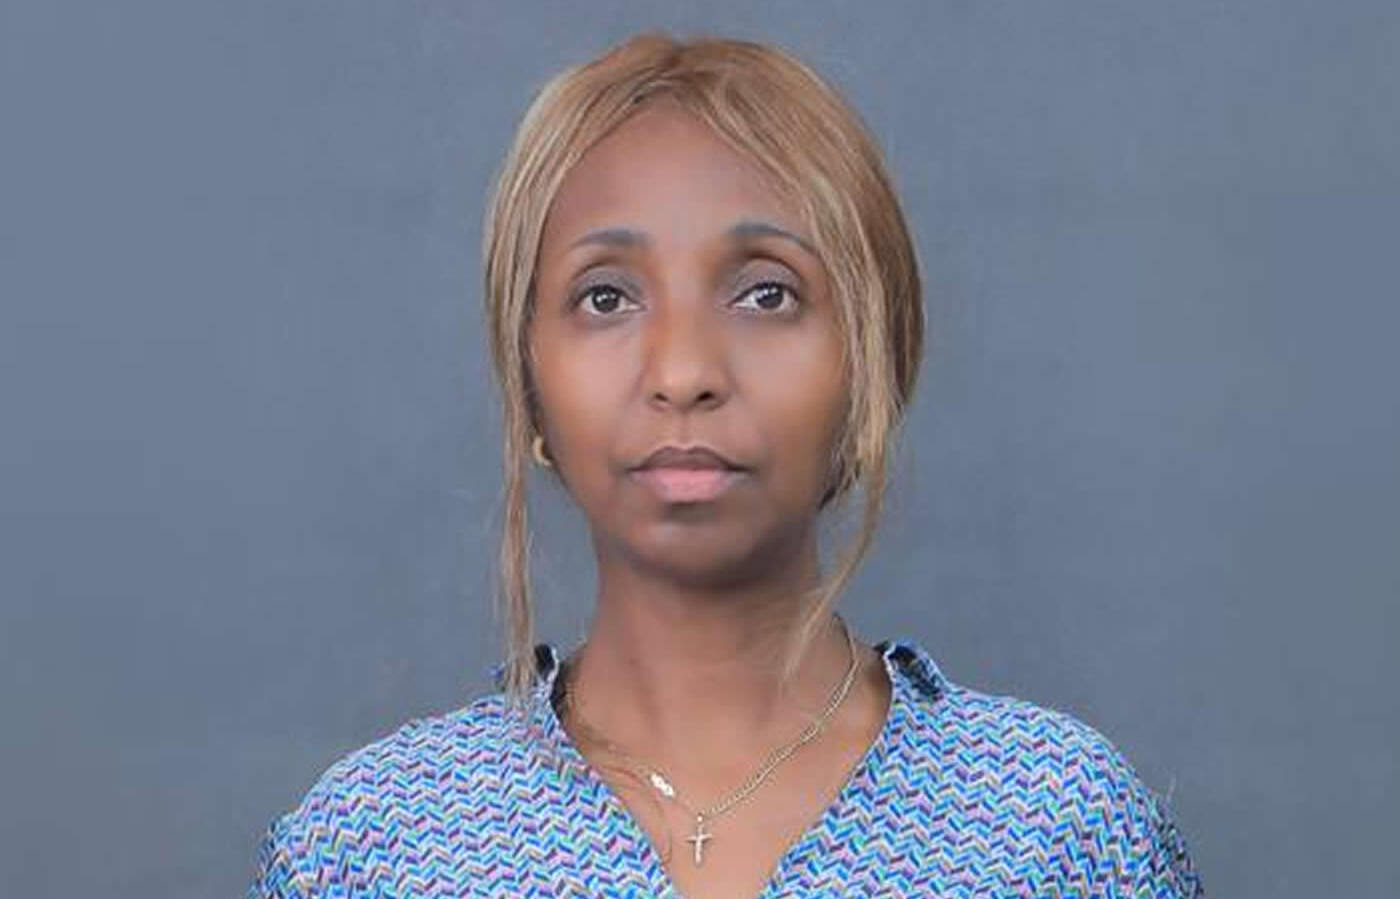
Frehiwot Alemayehu joined Zemen Insurance in March 2026 with a mandate to strengthen one of the country’s younger insurers as the market enters a period of rapid change. A veteran of the insurance sector with nearly two decades of experience, she moved to Zemen after a long career at Awash Insurance, where she served as Deputy CEO and Chief Customers’ Officer.
Her career has also included board-level roles, including at Awash Bank and Ethiopian Reinsurance Company, giving her experience across insurance, banking and reinsurance. At Zemen, she has taken on the challenge of improving operational performance, strengthening underwriting discipline, expanding products and positioning the company for long-term growth.
In this interview with Birrmetrics’ Amanuel Kindeya, Frehiwot discusses the economics of insurance, from pricing risks and managing claims to capital requirements, life insurance ambitions and the pressures facing insurers as inflation and foreign-exchange shortages reshape the cost of doing business.
BirrMetrics: You spent nearly two decades at Awash Insurance. Why did you decide to leave such an established insurer and take on the challenge of leading a much younger company like Zemen Insurance? When the board approached you, what did it want you to help change?
Frehiwot Alemayehu: First, I would like to express my sincere appreciation to Awash Insurance. I spent most of my professional journey there, and the company had a major role in shaping me both personally and professionally. I had the opportunity to work with experienced professionals, take on different responsibilities and grow as a leader. I remain grateful for that experience.
My decision to join Zemen Insurance was not simply about moving from one company to another. It was about taking on a new challenge and contributing to the growth of a company with strong potential.
When the Board approached me, it was looking for leadership that could help strengthen the company’s governance, improve operational performance, increase profitability, accelerate digital transformation and support the development of new products. The goal was to build a stronger foundation for sustainable growth.
Those priorities matched my own belief about where the insurance industry is heading. I saw an opportunity to contribute not only by leading the company today, but also by helping shape its future direction.
Women have worked in the insurance industry for decades, yet relatively few have reached senior leadership positions. Where do you think the leadership pipeline breaks down? Did you ever feel you had to prove yourself more than male colleagues, or face barriers that were not always visible?
The country’s insurance industry is fortunate to have many talented and capable women. However, when you look at senior executive and board-level positions, the number of women declines significantly. I do not believe this is because women lack the competence, ambition or commitment required to lead. In many cases, it is related to organisational culture, limited access to leadership opportunities and unconscious bias.
Throughout my career, I focused on delivering results, maintaining integrity and continuously improving myself. Like many women in leadership, I sometimes felt I had to demonstrate my capabilities more than once before gaining the same level of confidence and recognition that others may receive more easily.
The biggest invisible barrier is often perception rather than policy. Sometimes, the challenge is not about formal rules, but how leadership potential is viewed and recognised. Fortunately, attitudes are changing, and I believe organisations are increasingly recognising talent based on merit.
I hope my journey encourages more women to pursue leadership roles and inspires companies to continue creating opportunities for capable women to contribute at the highest levels.
Zemen's premium income grew by 28.27 percent to 699.5 million birr in 2024/25, but the company missed its target. What was the target, why was it missed, and what exactly does Zemen's ambition to become one of Ethiopia's five largest insurers by 2035 mean?
We are pleased with the growth we achieved during the year, even though we did not fully meet our internal premium target. The shortfall was mainly due to changing market conditions, intense competition, and slower-than-expected growth in some business segments.
That said, we don't measure success by premium income alone. Our vision of becoming one of the country’s top five insurers by 2035 is about building a company that is financially strong, well governed, innovative, and trusted by customers.
For us, success means growing responsibly, strengthening our capital, providing excellent claims service, embracing digital technology, improving operational efficiency, and creating lasting value for our shareholders and customers. Sustainable growth is far more important than rapid growth achieved at the expense of sound underwriting.
The company reported profit before tax of 211.8 million birr. How much came from insurance underwriting and how much from investment income? Is Zemen profitable because it successfully prices and manages risk, or mainly because it earns interest by depositing shareholders' and policyholders' funds in banks?
Like any successful insurance company, our profitability comes from two complementary sources: underwriting and investment income. During the financial year ended 30 June 2025, our underwriting operations generated an Insurance Service Result of 194.5 million birr, while our investment portfolio contributed Net Investment Income of 115.6 million birr. Together, these supported our profit before tax of 211.8 million birr.
That said, our long-term strategy is very clear. We want underwriting, not investment income, to be the primary driver of our profitability. Investment income is an important contributor, but sustainable success comes from selecting the right risks, pricing them correctly, managing claims efficiently, and maintaining strong underwriting discipline.
We are building a company whose profitability is based first and foremost on sound Insurance fundamentals, with prudent investment management providing additional support.
What did Zemen’s underwriting performance look like in the latest financial year? Specifically, what were the underwriting result, loss ratio, expense ratio and combined ratio, and what do these indicators reveal about the strength of the company’s core insurance business?
Our underwriting performance remained strong during the year, reflecting the quality of our risk management and underwriting discipline. We recorded an underwriting result of 194.5 million birr, showing that our core insurance operations continued to generate positive returns.
According to our audited financial statements prepared under IFRS 17, our loss ratio was 43.36 percent, expense ratio was 36.05 percent, and combined ratio stood at 79.4 percent. In practical terms, this means that for every 100 birr of insurance revenue generated, about 79.40 birr was used to cover claims and operating expenses, leaving an underwriting margin of around 20.60 birr before investment income.
A combined ratio below 100 percent indicates that an insurer’s core underwriting activities are generating a profit before considering investment returns. Our 79.4 percent combined ratio reflects the impact of disciplined risk selection, effective claims management and cost control.
We remain focused on strengthening these fundamentals as we continue to build a sustainable insurance business that creates value for customers and shareholders.
Zemen Insurance’s paid-up capital reached 415.3 million birr. Is this level of capital sufficient to support the company’s growth ambitions and the risks it plans to underwrite, or should shareholders expect further capital injections as the business expands?
Our current capital base is sufficient to support our existing operations and meet regulatory requirements. At the same time, we recognise that future growth will require additional capital as the business expands.
As the industry moves towards a risk-based capital framework, maintaining a strong capital position will become increasingly important. We therefore consider capital planning a strategic priority and will continue working closely with our shareholders to ensure the company remains well positioned for sustainable growth.
Claims settlement is often the moment when customers judge the value of an insurance company. What is Zemen’s average claims-settlement period, and what specific improvements should customers expect to see during your first year as CEO?
I understand why customers often judge an insurance company by how it handles claims. At the end of the day, that is when our promise to customers is truly tested.
Our goal is to make the claims process faster, simpler and more transparent. During my first year as CEO, customers should expect three key improvements: faster claims assessment and settlement through process improvements and greater use of technology; better communication, with customers receiving regular updates rather than being left uncertain about the status of their claims; and a smoother customer experience by simplifying documentation where possible while maintaining appropriate controls.
Price competition has been a recurring challenge in the insurance market, with concerns that some insurers are sacrificing underwriting discipline to win business. Are premiums still being set below the true cost of risk, and what role should the regulator play in addressing this issue?
Competition is healthy for customers and for the industry when it is driven by efficiency, innovation and sound business practices. However, when premiums are set below the actual cost of the risks being assumed, it creates challenges that eventually affect the entire market, including customers.
Insurance pricing must be based on proper risk assessment and technical analysis. Each insurer has a responsibility to maintain underwriting discipline, while the regulator has a critical role in ensuring market stability, promoting fair competition and protecting policyholders.
Sustainable growth cannot be achieved through pricing that does not reflect underlying risks. In the long run, disciplined underwriting benefits the entire insurance sector by supporting stronger and more resilient companies.
Zemen had announced plans to enter the life insurance market by mid-2026. Has the company launched the product as planned? If not, what specific regulatory, operational or capital requirements are delaying the rollout?
Life insurance remains a strategic priority for us because we see significant potential in this segment. However, entering the market requires careful preparation to ensure the business is built on a strong foundation.
The process involves securing regulatory approvals, completing actuarial assessments, developing appropriate products, establishing the required technology systems, building the necessary expertise and ensuring adequate capital support.
We are progressing on these areas and want to enter the market with products that are sustainable, competitive and designed to meet customer needs. For us, it is important to launch life insurance in a way that ensures long-term success rather than simply meeting a timeline.
Inflation and foreign-exchange pressures have increased the cost of claims, from vehicle repairs and imported spare parts to medical services and construction materials. How is Zemen recalibrating premiums, insured values and underwriting practices to keep pace with rising costs while ensuring coverage remains affordable for customers?
The current economic environment presents challenges for both insurers and customers. Rising costs require insurers to continuously reassess their approach to ensure customers maintain adequate protection while the business remains financially sustainable.
At Zemen Insurance, we regularly review insured values, pricing, underwriting assumptions and claims costs to ensure our products remain aligned with changing market conditions. We also encourage customers to review their insured values periodically and update them where necessary to avoid being underinsured.
Alongside pricing and underwriting adjustments, we are focusing on improving claims management, strengthening relationships with service providers and enhancing operational efficiency. These efforts are aimed at ensuring we continue to provide fair, timely and reliable service while navigating the pressures created by the current economic environment.




