

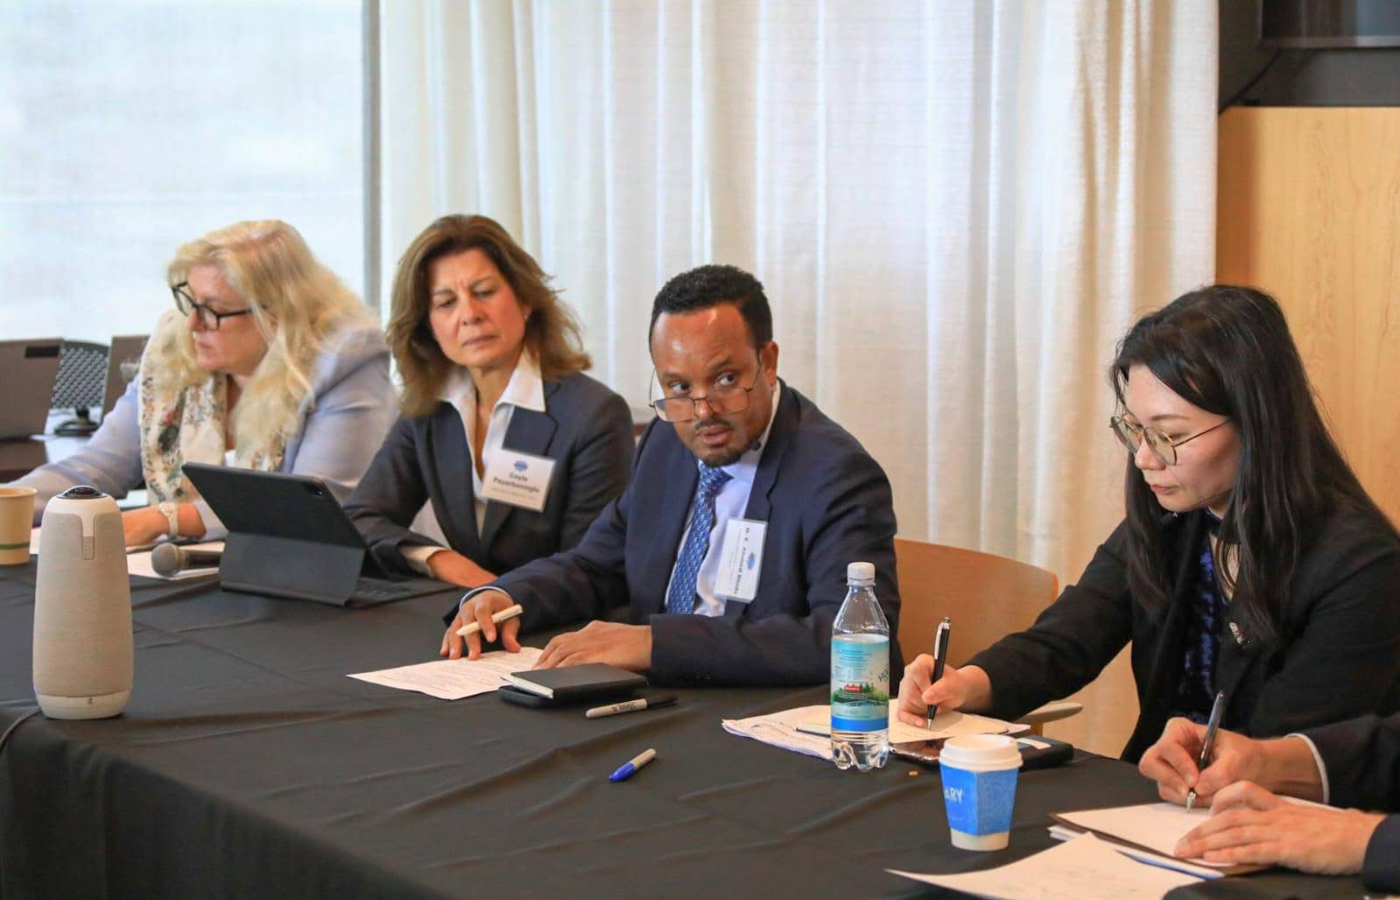
Finance Minister Ahmed Shide has called for a more transparent and equitable framework governing “Preferred Creditor Status” (PCS), arguing that the current system favours certain international lenders and slows debt restructuring for developing nations.
Speaking at the 8th Interdisciplinary Sovereign Debt Research and Management Conference, held alongside the IMF and World Bank Annual Meetings, Ahmed said PCS remains a respected principle but is applied inconsistently. The lack of clarity on who qualifies and under what conditions, he said, introduces uncertainty that complicates negotiations and shifts the burden onto domestic and bilateral creditors.
Ahmed proposed that preferential status be granted only to lenders providing concessional, counter-cyclical, and reform-supportive finance. He also called for the debate on PCS to move from informal creditor-led platforms to inclusive global forums such as the G20–IMF Roundtable or the UN’s Financing for Development process, allowing developing countries to have a substantive role in shaping the rules.
Ethiopia’s intervention comes amid ongoing efforts to resolve its sovereign debt under the G20 Common Framework, following a 2023 default on a one billion US dollar Eurobond. The country’s external public debt stood at about 31 billion US dollars in late 2024, with debt service expected to absorb nearly a quarter of exports in 2025 without restructuring.
Official creditors, including China and France, agreed in March 2025 on 2.5 billion US dollars in debt relief through maturity extensions and lower interest rates, formalised in July. Talks with private bondholders remain stalled due to disagreements over value-recovery instruments and downside protections. Ethiopia continues negotiations through Lazard and White & Case, while bondholders, advised by Ankura and Weil Gotshal, have signalled potential legal action.
The IMF’s September 2025 Debt Sustainability Analysis rated Ethiopia’s debt-carrying capacity as “weak” but noted improvements in fiscal consolidation, inflation control, and exports, which reached 8.3 billion US dollars in 2024/25. The IMF’s 3.4 billion US dollar Extended Credit Facility has disbursed more than 2.5 billion US dollars, contingent on securing 3.5 billion US dollars in total debt relief to restore sustainability.
Eurobond prices above 70 cents on the dollar reflect expectations of moderate restructuring but continued uncertainty over timing and scope of a final deal. Both the IMF and World Bank have urged quicker creditor coordination to restore market access.




