

Ethiopia is attempting a financial experiment few developing economies have dared: building a capital market from scratch while grappling with a chronic shortfall in national savings. The stakes are high. Without sufficient domestic savings, investment falters; without investment, growth slows. Yet if the fledgling market succeeds, Ethiopia could leapfrog traditional development pathways, attracting capital and fostering entrepreneurship in ways that defy conventional expectations.
“If Ethiopia allowed its financial market to lead freely, it could make a very surprising transition compared with other countries,” says Tewodros Mekonnen, a macroeconomic expert. “Increasing national savings is critical for its success.”
At the heart of Ethiopia’s economic challenge lies a persistent imbalance between savings and investment. Capital in Ethiopia amounts to roughly 40 percent of GDP, yet national savings linger at only 22 percent. Economists warn that this deficit constrains both government and private-sector investment, leaving many projects unfunded and opportunities untapped.
“This gap between savings and capital is the country’s core deficiency,” explains Tewodros. “An external economic deficit can trigger an internal one, and vice versa. Without closing it, the capital market cannot function efficiently.”
The problem is not unique to Ethiopia, but the scale is. In most developing economies, savings can be mobilised via remittances, foreign investment, or government borrowing. Ethiopia relies heavily on domestic government and private-sector capital, a dependency that makes the country vulnerable to policy missteps and administrative inefficiencies.
Capital in Ethiopia comes from two main sources: government coffers and private companies. While private firms respond to market pressures, government savings are guided by policy, giving the state enormous leverage over the pace and direction of the capital market.
“Government enterprises, like private ones, need a policy and strategic framework suitable for the market,” Tewodros notes. “The past two to three years have seen the investment gap relative to GDP narrow slightly, hovering around 18-20 percent. But national savings remain volatile, ranging from 10 to 24 percent of GDP.”
Experts argue that government spending must be targeted at foundational investments—roads, electricity, education, and health—that underpin a functioning capital market. Budget deficits and capital wastage, they warn, should not undermine the system.
“Direct monitoring must be conducted on the implementation of government resources,” says Jemal Ahmed, a finance specialist. “We need to conserve resources to establish a fundamental data system for the capital market, improve market conditions, and expand transparency.”
The persistent shortfall in savings limits the ability of the government and private sector to fund investment. Economists warn that without deliberate policies to increase national savings, capital markets will struggle to channel funds to productive projects.
“Delivering savings to investment is not enough,” Tewodros stresses. “It requires follow-up, efficient allocation, and ensuring that capital reaches the right users.”
The government has several tools at its disposal: tax incentives for savings, policy guidance on public investment, and regulations that encourage private firms to retain profits for reinvestment. Yet the execution remains uneven, and gaps in data and information management have hampered progress.
The Ethiopian capital market ecosystem remains nascent. Private enterprises, banks, and brokers all have roles to play, but participation is uneven. While banks have shown interest in trading and interbank lending, brokers—the intermediaries critical for facilitating transactions—remain underrepresented.
“The development of the interbank lending system, permitted by the National Bank, paves the way for capital-market growth,” says Tilahun E. Kassahun, CEO of the Ethiopia Securities Exchange (ESX). “Securities trading is already improving market efficiency, and monetary policy is helping prevent a return to old practices.”
Yet challenges remain. Investor accounts are opening at a steady pace, but low participation from brokers limits market depth. Expanding communication channels and improving financial literacy are critical next steps.
Institutional investors, meanwhile, are highly sensitive to both perception and the available national capital reserve. A limited pool of domestic capital constrains the size and ambition of investments, which in turn affects confidence and participation.
One of the most pressing challenges is financing Ethiopia’s next generation of innovators. Young entrepreneurs and idea generators struggle to access capital, a problem compounded by the low rate of national savings.
“When compared to the current reality on the ground, the financing problem for youth and idea generators is a challenge that demands change,” Tewodros observes. “Capital requires focusing on conditions where its reach to the right users can be ensured.”
Experts emphasise that the market must go beyond channeling savings to traditional investments. Venture capital, start-up financing, and support for high-potential sectors—technology, agriculture, and manufacturing—are crucial for long-term competitiveness.
Ethiopia’s ongoing financial liberalisation and monetary reforms are closely intertwined with capital-market development. Exchange-rate policies, interest-rate management, and regulatory oversight all affect the ability of investors to deploy capital efficiently.
“The positive aspect that securities trading brings to the efficiency of the capital market is an amazing success,” says Tilahun Kassahun. “Monetary policy is of great help in preventing a return to previous operational methods.”
Central-bank interventions aim to ensure liquidity and a steady market flow. At the same time, they guard against overreach by preventing any single institution from gaining undue advantage through government support. These measures, experts say, are essential to building credibility in a market that is only just learning to operate independently.
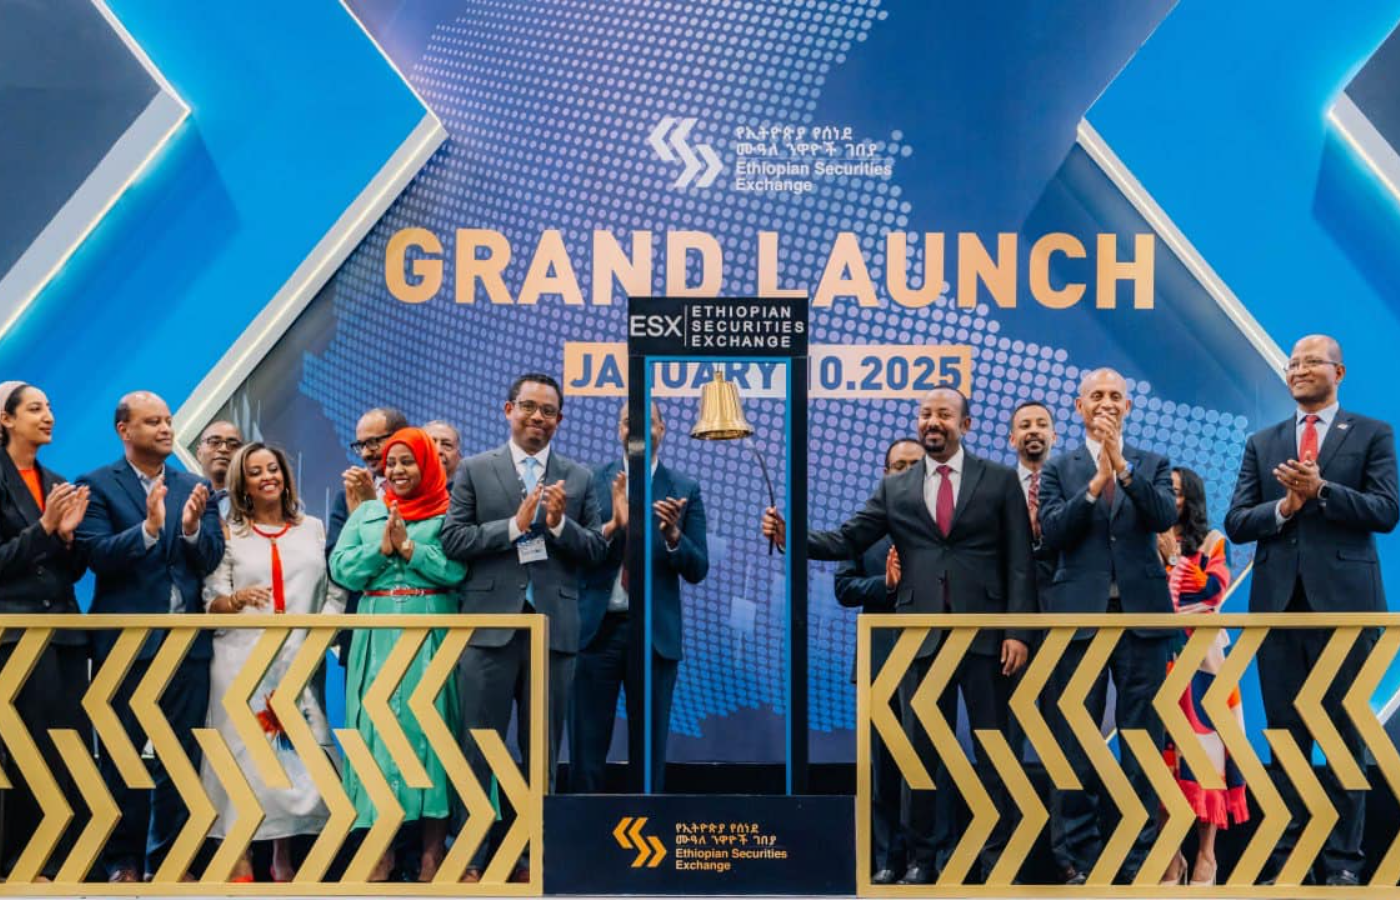
Despite early progress, the Ethiopian capital market faces multiple risks. Weaknesses in data management, low participation from brokers, and limited domestic savings could slow growth. Structural inertia—both cultural and institutional—poses additional hurdles, particularly as new investment products and market mechanisms are introduced.
“The assurance of market reliability begins with foundational systems,” Jemal Ahmed warns. “If these conditions are not addressed in time, they could pose challenges to capital-market development.”
Institutional memory and previous investment experiences can also complicate reform. Investors accustomed to traditional, state-directed channels may resist new methods, delaying the adoption of more efficient mechanisms.
Yet opportunities abound. A well-functioning capital market could attract domestic and international investment, foster entrepreneurship, and improve Ethiopia’s global competitiveness. Experts agree that building an interconnected, transparent system is essential.
Brook Taye, CEO of Ethiopian Investment Holdings, calls on licensed institutions to play their part: “Capital-market service providers, please do not neglect your given licenses.” Currently, Ethiopia has 13 licensed providers, including four investment banks, but more engagement is needed to deepen the market.
If savings rise, governance improves, and policy interventions are consistently applied, Ethiopia’s capital market could transform the economy, creating a diversified, resilient, and investment-driven growth model. The experiment is risky, but the potential payoff is extraordinary.




