

Young Staff Say the Job Feels More Like Sales Than Finance
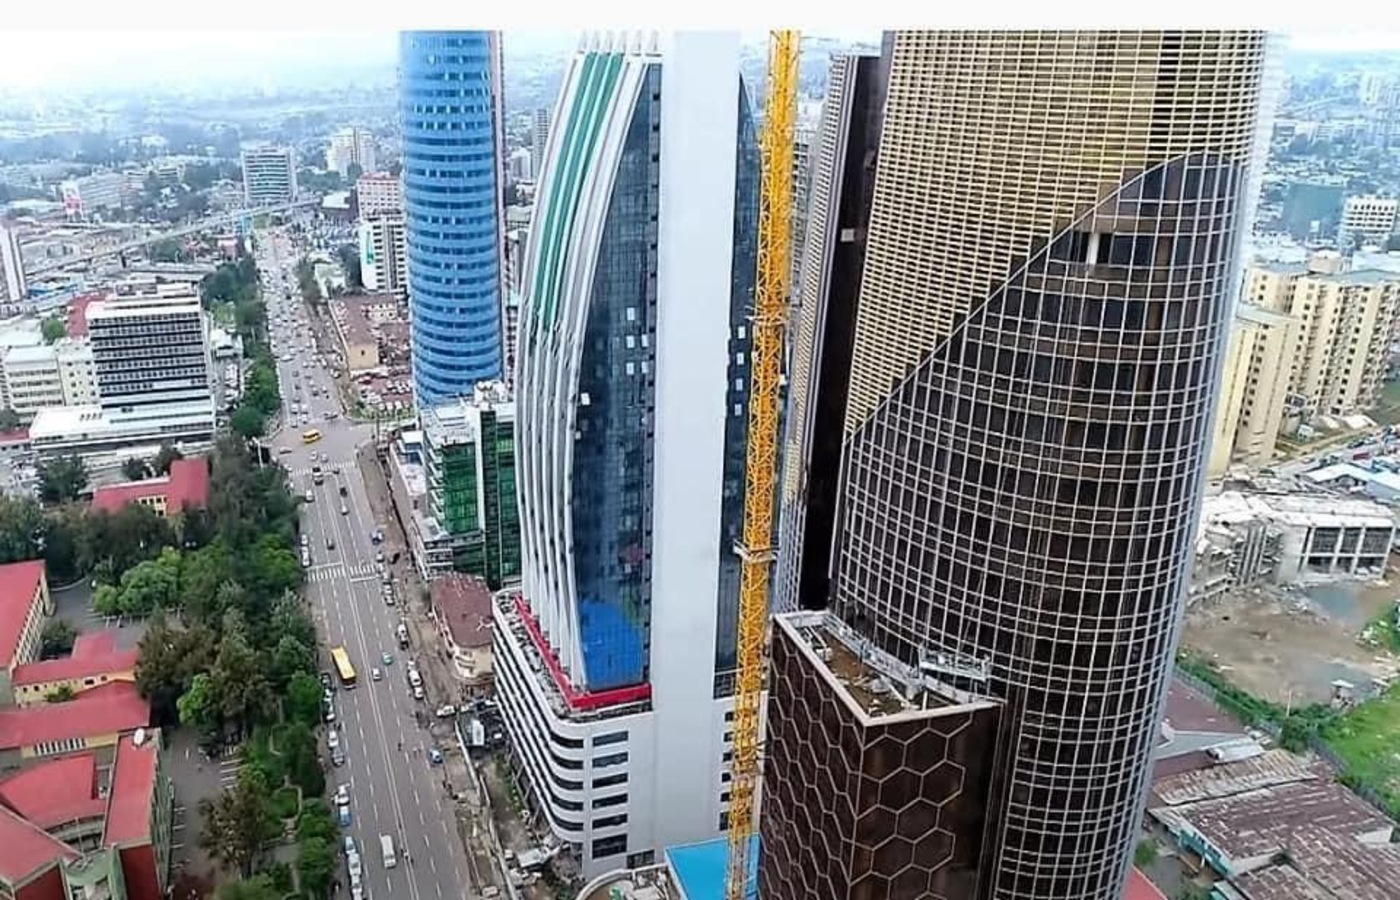
Megenagna, one of Addis Ababa’s busiest thoroughfares, is crowded with cars, pedestrians, and street vendors. Among them, young bankers weave through the crowd, approaching passers-by with a single mission: deposit mobilisation. The grandeur of modern banking remains behind glass, while the streets are where the real work—and the strain—happens.
This scene is familiar across Ethiopian banking. Rising living costs are making it harder for staff to attract clients and secure initial deposits. On social media, particularly TikTok, complaints have surfaced that some bankers are allegedly covering initial deposits from their own pockets, highlighting the growing strain on frontline staff. Rarely, an employee will take to their screen to share a positive account of their daily routine.
Yohannes Gebreab, name changed for anonymity, joined the banking sector recently, seeking better pay. While his salary meets expectations, it comes “with stress and unrealistic targets,” he told Birrmetrics. “The targets we are given are inappropriate. The number of deposits and new customers we are expected to secure is not fair.”
At his bank, staff must recruit 65 new customers each month, each with an initial deposit of 50 birr. “Some clients are willing to support you but not the initial deposit,” he explained. “As a result, you end up covering the amount yourself.”
Abraham Tehsome, name changed for anonymity, described the strain of frontline banking with noticeable frustration. He said he spends at least 1,000 birr each month to cover initial deposits for clients unable to meet the requirement. “Supervisors and credit officers do not share in onboarding; the responsibility—and the cost—falls entirely on us,” he said. “On top of door-to-door marketing, staff end up spending between 1,800 and 2,200 birr monthly just to meet targets.”
He added that poor communication between branch-level staff and senior management exacerbated the problem. Management often displayed a top-down, rigid approach, dismissing explanations and failing to empower younger staff. “In this environment, our core skills—market prediction, economic analysis, client relations, and management—feel meaningless when achievement of arbitrary targets is the only metric that matters,” he said.
Desta Berhe, president of the Finance Industry Federation under the Confederation of Ethiopian Trade Unions, said some banks have resisted the proclamation, imposing workloads on employees beyond permitted limits. In the 2024/25 fiscal year, the federation won a lawsuit against six private banks over workers’ rights. “This came after many back-and-forths with the board and management,” he told Birrmetrics.
The federation highlighted cases where staff were inappropriately transferred between branches, agreements with employees were not honoured, and opportunities for promotion were withheld.
Banks routinely require staff to acquire new customers, enrol clients in mobile, ATM, and internet banking services, and mobilise deposits—reflecting standard operational expectations for frontline employees. These targets are made more difficult by limited product appeal, negative saving rates, and the double tax applied to deposit interest, leaving staff with little convincing power when approaching potential customers. Access to credit for small businesses also remains constrained, as the banking system continues to prioritise corporate clients, underscoring a structural gap in Ethiopia’s financial sector.
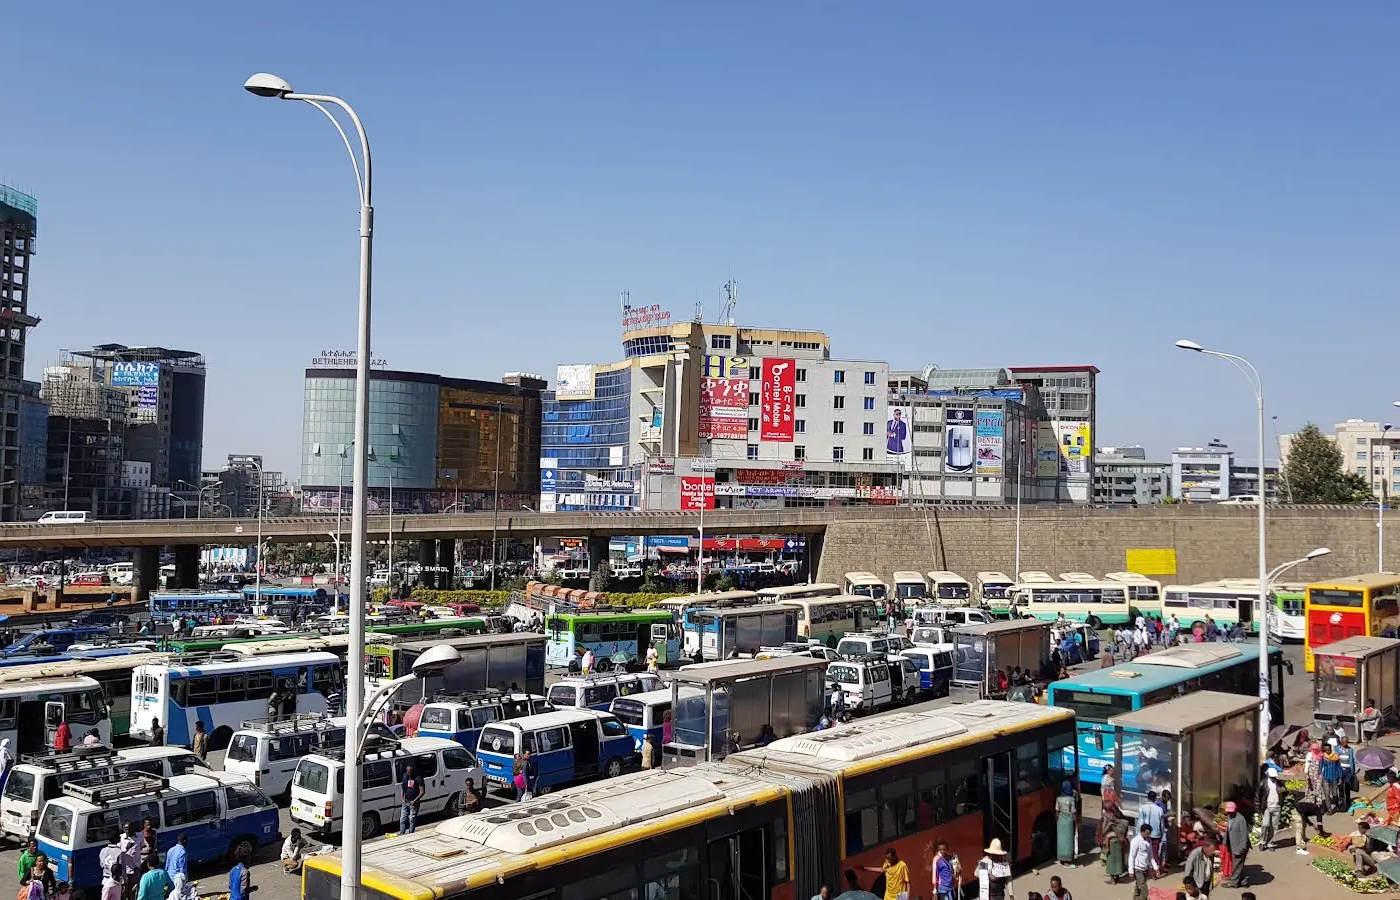
Industry experts cite multiple factors behind the trend, noting that the sector’s heavy reliance on physical, branch-based operations has intensified challenges in an increasingly digital era. The banking industry is gradually embracing digital solutions, with some banks introducing paperless operations. By mid‑2024, Ethiopia’s banking sector had seen rapid digitalisation, with around 39.6 million registered mobile banking accounts and approximately 107.5 million mobile money users, marking a 56.6 percent year-on-year rise. Internet banking users reached nearly 12.2 million.
Aminu Nuru, a financial expert based in Qatar, said Ethiopia lags behind many international banking practices, where institutions have moved beyond simple branch-based operations. “When I joined the bank I am currently working at, there were 39 branches; now that number has fallen below 30,” he said. “Yes, branches are expanding in Ethiopia, but that does not mean the same approach should be applied. What is needed is a strategic plan that addresses the deep-rooted challenges hindering the development of the banking industry.”
Manual processes continue to weigh heavily on efficiency. Loan processing, credit assessment, and internal risk checks are largely done by hand, while limited automation and outdated core banking systems intensify pressure on front-line teams.
Yisak Teka, a strategist and risk analyst, said branch-based operations continue to place considerable pressure on front-line staff, who must handle large volumes of deposits, withdrawals, and customer inquiries. “Rapid workforce expansion has not always translated into productivity gains. Many employees handle repetitive or low-value tasks, even as workloads remain high,” he told Birrmetrics. Frequent shifts in regulations add another layer of complexity. “Staff must balance compliance monitoring, credit documentation, and operational risk checks alongside core duties,” he noted.
Experts highlight liquidity challenges in the country as a key factor contributing to heavy workloads for bank employees, who are often tasked with meeting targets in an economy already strained by rising living costs. Many staff are required to achieve monthly goals, such as opening new bank accounts, with failure affecting performance evaluations and slowing prospects for promotion. Observers argue that the sector’s reliance on such traditional performance models is increasingly outdated.
Less than 0.4 percent of depositors hold more than half of total deposits in Ethiopia’s banking sector, according to the National Bank of Ethiopia’s 2024 financial stability report. Many belong to state-owned enterprises, creating a structural risk if a few major clients move their funds. The sector’s loan and bond to deposit ratio is close to 88 percent, indicating that most of the resources mobilised by banks are already committed. Only a limited portion of assets is available in cash to meet immediate obligations. Central bank stress tests show that liquidity ratios could fall below regulatory requirements if the largest depositors withdrew their funds, leaving several banks at risk of breaching minimum thresholds.
Some customers feel the pressure too. “I have accounts with over five banks, but I only actively use one,” said Dagmawit Endashaw, a banking customer willing to engage with staff who reach out to her.
“This type of deposit-attraction model won’t bring value to any bank,” said Desta. “Banks should focus on creating a sense of belonging for their customers through attractive products that encourage them to deposit even their most valuable assets. Customers should also be included in loan opportunities.”
Yisak noted that daily cash management, internal fund transfers, and contingency planning under liquidity constraints place significant strain on front-line staff.
Ethiopia is pursuing an ambitious modernisation of its financial sector. Reforms introduce an interest-rate-based monetary framework anchored by open market operations, a formal policy rate, banks rushing to meet minimum paid-up capital thresholds, the development of capital markets, and new liquidity facilities. A strengthened legal framework has expanded the National Bank of Ethiopia’s autonomy, established a Monetary Policy Committee, and ended direct central bank financing of the government. The foreign exchange system has been liberalised through interbank trading and the removal of surrender requirements, while a new banking proclamation and Basel-aligned capital directive have updated regulatory standards.
The reform package also includes the Ethiopian Securities Exchange, partial privatisation of state firms, and initiatives to expand digital finance and financial inclusion. Alongside the shift to a market-based foreign exchange system, foreign bank ownership of up to 40 percent is now permitted, creating a new industry norm and prompting frequent directives from Biheraw Street to Senga Tera.
Experts say the reforms lay the foundation for the sector to compete with foreign entrants. They note that liberalisation is expected to address challenges faced by employees and meet customer demand by enabling the introduction of innovative products that have long been neglected under limited domestic competition.
Yisak noted that high-value depositors could shift to foreign entrants offering better rates, advanced technology, and superior service quality. “There is also the potential for a two-tier market, with foreign banks focusing on corporate and affluent clients, leaving domestic banks with riskier or less profitable segments,” he added. He warned that failure to modernise or optimise operations could lead to margin compression and increased operational pressures for local institutions.
“Extensive branch networks and deep knowledge of the local market allow domestic banks to serve underbanked populations effectively,” he said. “Regulatory safeguards, such as the 40 percent cap on foreign ownership, provide a buffer, while opportunities exist to differentiate through SME banking, digital channels, and agent networks.”
To address underemployment, heavy workloads, and mounting competitive pressures, Yisak urged banks to accelerate digital transformation and workflow automation, while investing in employee training and talent development. He emphasised the importance of rationalising branch networks, leveraging agent banking, establishing shared service centres for back-office and compliance functions, and streamlining regulatory and reporting requirements.
Yisak added that banks should “develop specialised business units for corporate, SME, and retail segments, explore fintech partnerships to drive service innovation, and target financial inclusion and underbanked markets to build sustainable revenue streams.” The reality on the ground, however, shows why such shifts are overdue. In Addis Ababa, the daily grind of young bankers—knocking on doors, pleading for deposits, and often paying out of pocket—shows the limits of the old model. Their experience is a reminder that the system must evolve into one where innovation, digitalisation, and empowered staff can finally meet the needs of ordinary customers.




