

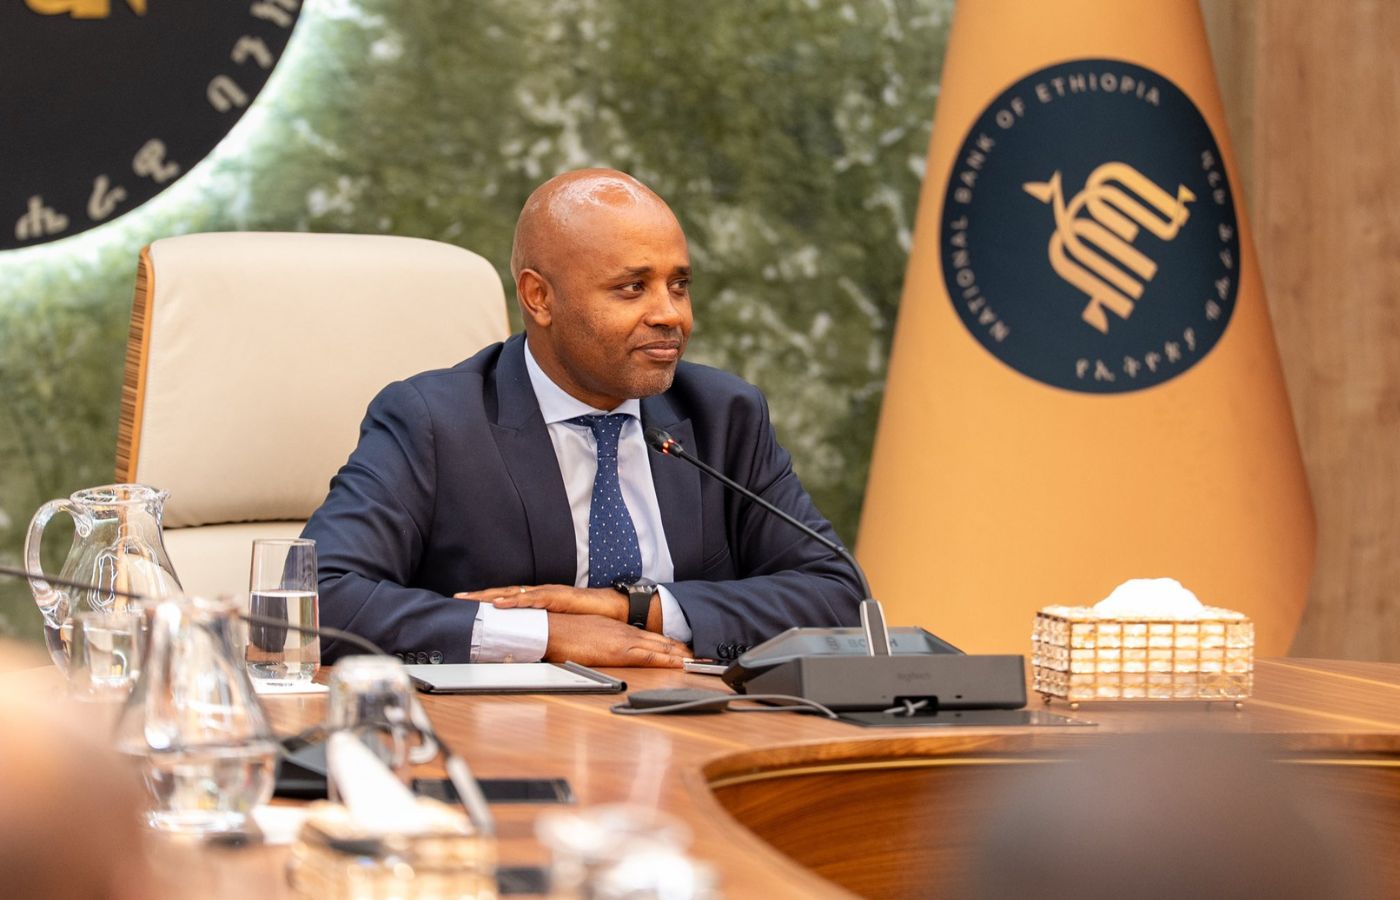
Central Bank Governor Eyob Tekalign (PhD) says Ethiopia’s monetary stance is “if anything, tighter than before” as the central bank replaces the blanket lending restriction with market-based tools
The removal of Ethiopia’s commercial bank credit cap does not represent an easing of monetary policy, National Bank of Ethiopia Governor Eyob Tekalign said, arguing that the measure must be viewed alongside a higher policy interest rate and new controls targeting individual banks.
Speaking to journalists following the seventh meeting of the central bank’s Monetary Policy Committee, Eyob said NBE was changing the instruments it uses to manage liquidity and inflation without retreating from its tight monetary policy stance.
“I want to be explicit on this point: this is a change in instrument, not a change in stance,” Eyob said.
The central bank announced the complete removal of the annual credit growth ceiling introduced in 2024, while raising its policy interest rate by one percentage point from 15 percent to 16 percent.
The existing corridor of three percentage points above and below the policy rate will remain unchanged.
According to the governor, the credit cap was introduced as a temporary measure to contain lending growth while NBE developed an interest-rate-based monetary policy framework.
“It has served that purpose, and its removal reflects the fact that the Bank now has a functioning interest-rate-based framework at its disposal,” he said.
The credit ceiling restricted how quickly commercial banks could expand their loan portfolios, giving NBE a direct mechanism to limit the growth of money and credit across the financial system.
Its removal will give banks greater flexibility to determine their lending levels and allocate loans across different sectors. However, Eyob said the policy-rate increase was introduced to offset the expansionary pressure that could follow the lifting of the ceiling.
“Because removing the cap on its own would ease pressure on credit growth, the Committee judged that an offsetting measure was required to keep the overall policy stance tight,” he said.
“The rate increase and the removal of the cap should therefore be read together: one instrument is retired, and the other is strengthened, so that the net effect is a monetary stance that is, if anything, tighter than before.”
NBE will also introduce a targeted additional reserve requirement for banks where regular assessments show that their loan-to-deposit ratios are contributing to inflationary pressure.
Unlike the credit cap, which applied an economy-wide restriction, the new mechanism will allow the central bank to impose additional reserve obligations on individual banks whose lending behaviour is considered a risk to price stability.
“This gives the National Bank a precise instrument to act on individual banks, rather than the economy-wide constraint the credit cap once provided, should credit expansion in any part of the system begin to threaten the inflation outlook,” Eyob said.
The shift comes as inflation has begun rising again following a period of sustained decline. Headline inflation reached 13.4 percent in May 2026, up from 11.7 percent in April and 9.7 percent in December 2025.
Food inflation stood at 15 percent in May, while non-food inflation reached 11.1 percent. The governor attributed part of the recent increase to fuel-supply disruptions linked to conflict in the Middle East.
NBE said the tighter stance remained necessary to manage inflationary pressure and achieve its objective of returning inflation to single digits over the medium term.
The central bank also introduced two foreign-exchange measures as part of the same policy package.
It reduced the mandatory surrender requirement on proceeds from goods exports from 50 percent to 30 percent, allowing commercial banks to retain a larger proportion of the foreign currency they receive.
Eyob said the reduction was intended “to strengthen export competitiveness, deepen the foreign exchange market, and improve price discovery.”
NBE also reduced its foreign-exchange commission rate from 2.5 percent to 1.5 percent to lower import-related expenses and limit the transmission of higher international prices into domestic inflation.
The governor said the five measures—the removal of the credit cap, the policy-rate increase, targeted reserve requirements and the two foreign-exchange adjustments—should be understood as a single and coordinated policy package.
“Taken together, these five measures reflect one consistent judgment by the Committee: that Ethiopia’s monetary framework has matured to the point where it can rely on indirect, market-based instruments,” Eyob said.
He added that this transition “must be matched by continued discipline, not by any easing of our resolve on inflation.”
The central bank’s assessment showed that Ethiopia’s economy continued to expand, with real gross domestic product growth estimated at 7.6 percent in the 2024/25 financial year. Growth is projected at 10.2 percent for 2025/26.
NBE also described the banking sector as resilient, citing improvements in deposit mobilisation, loan collection, asset quality and capital buffers. The loan-to-deposit ratio of private banks declined to 72.7 percent from 90.3 percent in 2022/23, reflecting improved liquidity management.
The Monetary Policy Committee is scheduled to meet again by the end of September 2026, although the governor said it could convene earlier if economic conditions warrant.




