

Ethiopia is moving to build a new layer of its housing-finance system, with a 100 billion birr mortgage refinancing company planned with support from the International Finance Corporation (IFC), Prime Minister Abiy Ahmed (PhD) said.
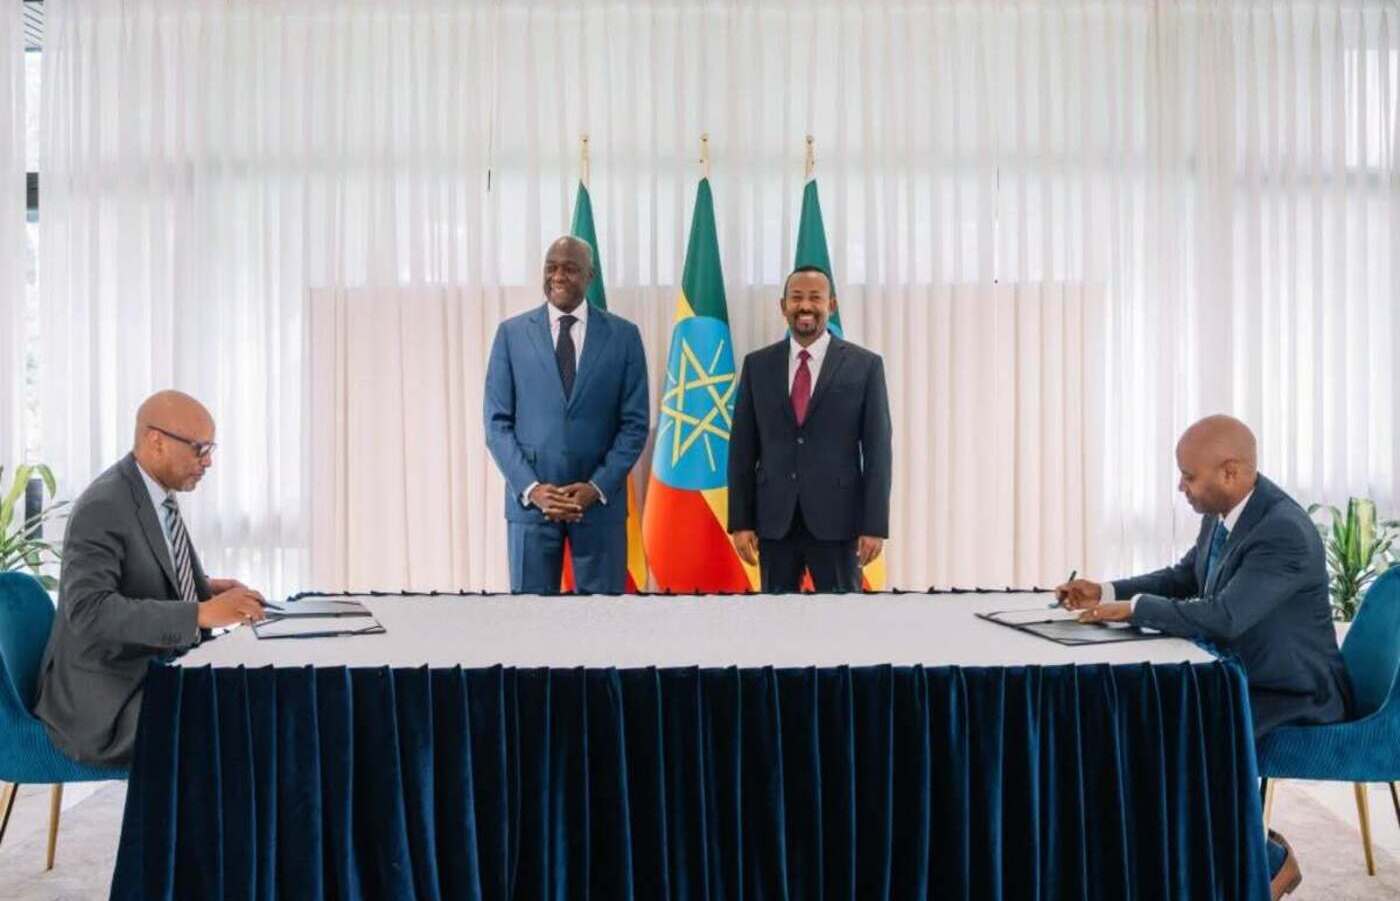
The National Bank of Ethiopia and International Finance Corporation have signed a cooperation framework for what Abiy described as the country's first specialised mortgage refinancing company. IFC is expected to contribute up to 200 million US dollars to the institution.
The proposed company is designed to tackle a less visible constraint on Ethiopia's housing market: how banks fund long-term mortgages.
Banks typically depend heavily on deposits to finance lending, while mortgages can run for many years. The resulting mismatch between short-term funding and long-term housing loans can limit banks' appetite and capacity to expand mortgage portfolios. A refinancing institution could provide banks with longer-term liquidity against eligible mortgage assets, allowing them to recycle capital into new housing loans.
That could prove more consequential than simply adding another lender to the market.
Ethiopia's mortgage market remains small and highly concentrated. The Centre for Affordable Housing Finance in Africa estimates outstanding mortgage loans at about 24.1 billion birr in its latest country data, with the Commercial Bank of Ethiopia accounting for roughly 69 percent of the portfolio.
The proposed 100 billion birr capital base is therefore striking in relation to the existing mortgage stock. The scale suggests the government is attempting to build an institution capable of supporting a much larger mortgage market rather than merely filling a funding gap at the margin.
For private banks, the change could be particularly important. Limited access to long-term funding has been one of the obstacles to building sizeable mortgage businesses, leaving housing finance heavily concentrated in CBE. A functioning refinancing market could lower the balance-sheet burden of holding long-duration housing loans and make the sector more attractive to private lenders.
But more liquidity will not by itself solve the country’s lhousing-affordability problem.
The country's banks have entered a new interest-rate environment following the National Bank's move to allow lenders to determine their own lending and deposit rates. Commercial-bank lending rates have generally remained high, making the cost of a mortgage a critical factor in determining whether additional funding translates into additional home ownership.
The refinancing company will therefore face a harder test than simply mobilising capital: it will need to help create mortgage products that households can actually afford.
Abiy linked the initiative to a government target of providing 1.5 million affordable homes and expanding private-sector participation in the financial system. The refinancing company would not itself deliver those homes, but could address a central financing bottleneck by creating a wholesale source of longer-term funding for banks.
The initiative also signals a potential change in the architecture of Ethiopian housing finance. Instead of each bank having to fund mortgages largely from its own deposit base, a specialised intermediary could connect banks with longer-term capital and allow mortgage lending to develop into a more scalable financial market.
The participation of IFC, the World Bank Group's private-sector arm, adds an international development-finance component to the effort. Its proposed contribution of up to US$200 million could help establish the institution's initial funding and credibility, although the structure and terms of the investment have not been disclosed.
The ultimate test, however, will be whether the new financing channel changes the economics of mortgages for households. Without lower funding costs, longer maturities, stronger credit infrastructure and a sufficient supply of affordable housing, a larger refinancing pool could expand mortgage lending without making home ownership materially more accessible.




