


Why Rising Forex Inflows Can’t Rescue the Birr
Ethiopia’s currency, the birr, has been sliding with unnerving persistence. The government’s decision July last year to embrace a market-based foreign exchange regime was billed as a modernisation step, promising efficiency, transparency, and greater investor confidence. Yet the reform has so far delivered a familiar outcome: depreciation.
The official rate has weakened steadily, while the parallel market—long the true barometer of sentiment—has widened its premium. The puzzle is that this depreciation comes at a moment when foreign exchange inflows look unusually healthy. The Ethiopian Investment Commission recently declared that the country had attracted four billion US dollars in foreign direct investment during the last fiscal year. The National Bank of Ethiopia reported exports of goods and services totalling 16.8 billion US dollars.
Remittances added another 7.1 billion US dollars, while grants and new loans contributed nearly four and a half billion US dollars. And that is not all: the IMF and World Bank have already disbursed over three billion US dollars, with pledges from the two approaching 17 billion US dollars over the next three years. Commercial banks, for their part, have boasted about higher allocations of hard currency to importers.

By any measure, these are respectable figures. They would normally reassure investors, strengthen the currency, and ease inflationary pressures. Instead, the birr has continued its descent, draining confidence and forcing authorities into a familiar cycle of intervention and warning. The NBE has held half a dozen auctions, placing more than 400 million US dollars on the table, while threatening to freeze accounts of those caught trading outside the official system.
The contradiction between inflows and exchange-rate weakness has drawn attention to the one element Ethiopia rarely confronts openly: capital outflows. The country may be receiving more dollars than ever, but money is leaving just as fast—if not faster. Some of these outflows are perfectly legal, such as debt repayments and profit repatriation by foreign firms. Others are less visible: illicit transfers through hawala networks, trade mis-invoicing, or hurried capital flight by nervous businesses. In a political economy shaped by uncertainty and chronic shortages, dollars are treated less as currency than as an escape route.
As one Ethiopian importer put it, the consequences are “devastating.” He explained that his firm had started with a paid-up capital of 200,000 US dollars, only to see it shrink to less than half that. “Currency floating and heavier taxation have left us with just 94,000. The tax system is flawed—it assesses us solely on margins without accounting for actual profits or losses. Tariff barriers have surged, and customs delays are choking supply chains.” His lament captures the daily frustration of businesses watching capital leak out faster than it flows in.

The authorities hoped to break this cycle by abandoning Ethiopia’s old, rigidly managed exchange-rate system. For decades the birr was propped up by central-bank diktat, creating distortions and fuelling black-market demand. The shift to a market-based regime—announced with much fanfare in June last year—was meant to align the official rate with economic reality, cut out arbitrage, and restore credibility.
The NBE’s bi-weekly auctions marked a symbolic departure from administrative allocation towards something resembling a market-clearing mechanism. In practice, however, the experiment has struggled to convince. A functioning float requires at least three conditions: deep reserves to smooth volatility, broad participation by private actors, and policy credibility. Ethiopia has little of any.
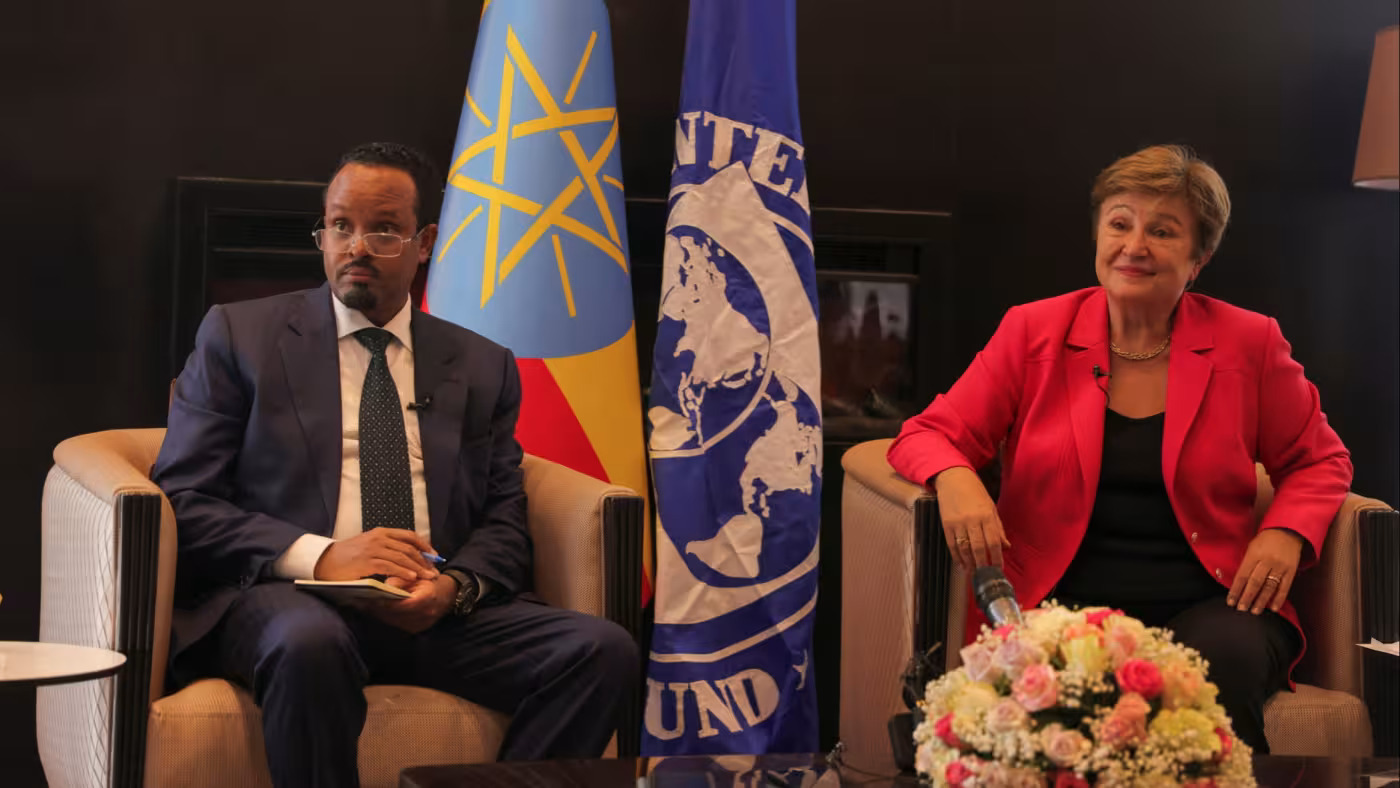
Foreign reserves stand at around four billion US dollars, enough to cover two and half months of imports. “Ethiopia brings in some foreign currency from exports, remittances, and investment,” noted Mikias Mulugeta, a financial consultant, “but the outflows from imports, debt payments, and profit repatriation are much larger.” With such an imbalance, the market sees a constant shortage of dollars—an imbalance that no auction system can disguise.
Participation remains thin: most private players still rely on parallel networks, doubting that the auctions offer reliable access. Credibility, meanwhile, is in short supply. After years of currency rationing, sudden directives, and opaque regulations, few believe that liberalisation will be consistent or sustainable.
Yet experience across Africa shows that liberalisation alone rarely suffices. Even after major FX reforms, Angola, Ethiopia, and Nigeria have retained some restrictions on current-account transactions; Egypt has kept one in place. These measures typically target specific operations or raise the cost of accessing foreign currency. They generate modest parallel-market demand but leave the real effective exchange rate largely stable. In Ethiopia, such restrictions persist, reinforcing the structural pressures that push demand outside the official system.
The International Monetary Fund, in a report published just last month, attributes much of the pressure to deeper structural features. A tightly closed financial account, limited instruments, and a concentrated banking sector continue to channel unmet FX demand into parallel channels. Ethiopia, the Fund notes, shares several traits with Angola during its own transition to a floating exchange rate, when the parallel market premium outpaced those of Egypt and Nigeria. Layered atop this are concerns over property rights, security, and conflict, all of which encourage capital flight.
The IMF advises a cautious, phased approach. Remaining current-account restrictions should be lifted gradually to reduce parallel-market incentives. Positive real interest rates would make holding birr-denominated assets more attractive. Opening the financial account should follow, once regulators can monitor cross-border flows and attract long-term capital safely. Expanding the interbank and FX markets, creating hedging instruments, and increasing competition in the banking sector—including through foreign participation—would improve price discovery and make FX intermediation more efficient.
For now, Ethiopia lacks the preconditions for a smooth float. Reserves stand at roughly four billion US dollars, covering barely two and a half months of imports. Participation in the official market remains thin, while private actors continue to rely on parallel channels. After decades of rationing, abrupt policy shifts, and opaque rules, credibility is in short supply.
Its liberalisation, introduced amid war-related instability, political fragmentation, and dwindling reserves, resembles less a carefully managed reform than an experiment born of necessity. For now, the birr’s trajectory reflects not the invisible hand of the market but the heavy shadow of outflows.
However, on paper, Ethiopia’s external accounts still look stronger than they have in years. FDI inflows of four billion US dollars place the country among the more attractive destinations in sub-Saharan Africa.
Exports of coffee, gold, flowers, and services such as aviation and logistics generated over 16 billion US dollars last year. Private transfers and remittances—often the most stable source of foreign exchange—added another seven billion US dollars. Multilateral partners contributed grants worth nearly two billion US dollars, while loans added 2.7 billion US dollars.
Such figures are not trivial. For comparison, Rwanda’s exports of goods amounted to around 1.5billion US dollars in 2024, while Kenya’s attracted about 2.5 billion US dollars in FDI. Ethiopia’s flows, then, should provide a decent cushion for its currency. And yet the birr continues to weaken, with the black-market premium climbing to multiples of the official rate.
The discrepancy lies in the balance between inflows and outflows. Imports still dwarf exports, particularly of fuel, machinery, and food staples. Debt repayments consume a growing share of reserves. Profit repatriation by foreign investors—perfectly legal—has risen as confidence wavers.
On top of that come illicit outflows. Hawala networks connected to Dubai and the United States offer faster transfers than Ethiopia’s banking system, despite being declared illegal by the Ethiopian government. The central bank recently vowed to pursue the matter through legal channels under international law. “Capital flight through hawalas drains liquidity from the formal system, depriving businesses of access to inputs and fuelling inflation,” observed Mikias.
Economists warn that the scale of these informal transfers is enormous. “More than half of Ethiopia’s economy operates informally,” explained Endalkachew Tsegaye, another financial expert. “Political instability accelerates capital flight, often exceeding official outflows. Since the economy isn’t developed enough to produce its own capital goods, Ethiopia leans heavily on hard currency—a dependence that drains reserves faster than they can be replenished.”
The result is a structural drain. Even as billions flow in, billions more seep out. Economists estimate that illicit financial flows from Ethiopia have at times exceeded official FDI. The net effect is that official statistics, however impressive, tell only half the story. What matters is not gross inflows but net availability—and that remains stubbornly negative.
For the Ethiopian business community, this arithmetic is all too familiar. Importers complain of months-long delays in securing foreign currency allocations. Exporters lament that profits vanish into bureaucratic bottlenecks. Ordinary citizens face rising living cost that erodes wages and savings. And the birr, weighed down by the gap between official optimism and lived reality, keeps falling.




