

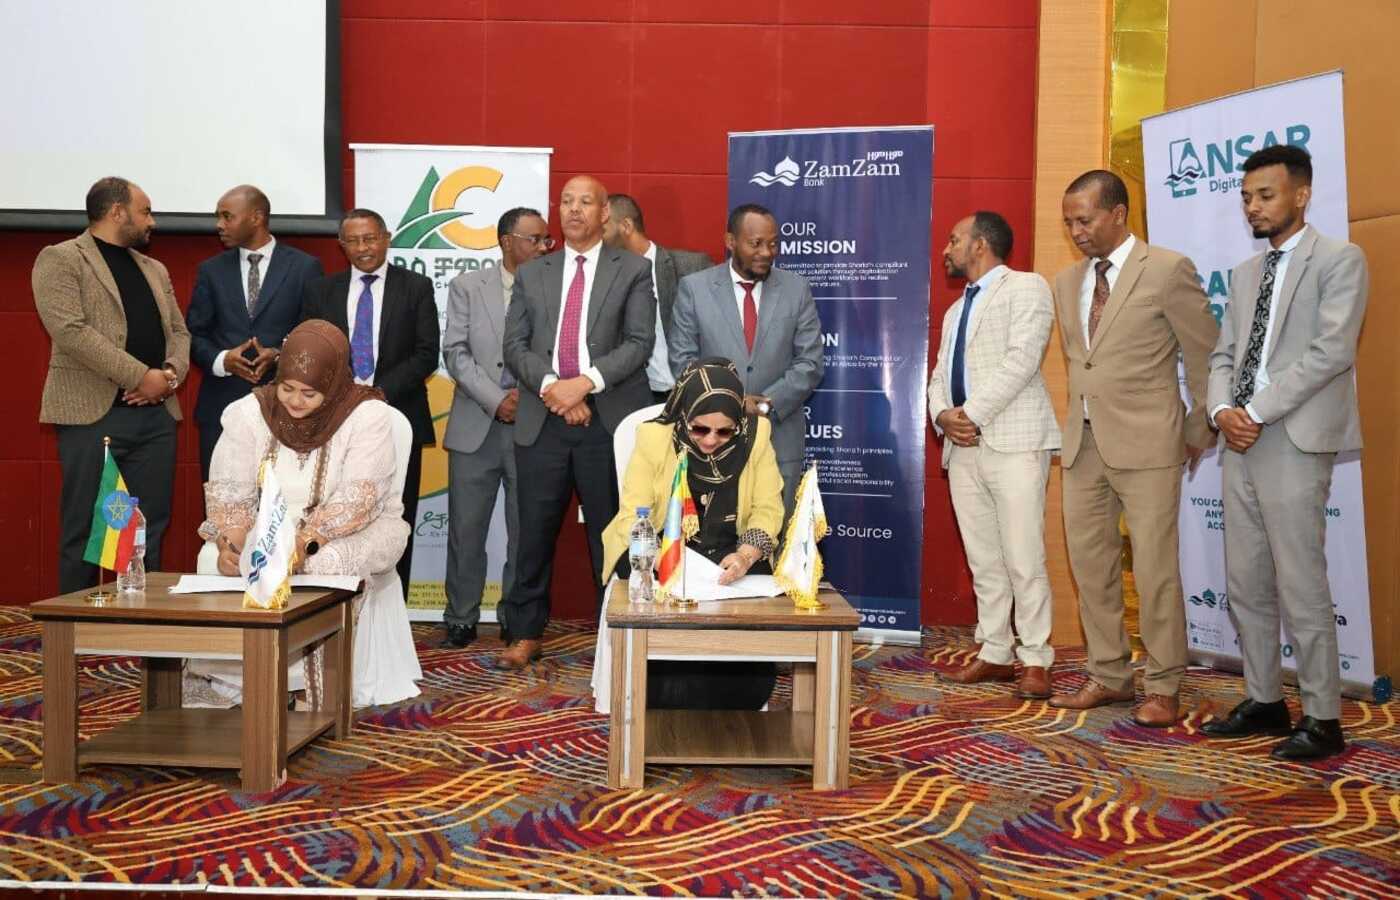
The Addis Ababa Chamber of Commerce and Sectorial Association has struck a partnership with ZamZam Bank to roll out a collateral-free lending scheme for small and medium-sized enterprises, adding momentum to Ethiopia’s gradual shift towards algorithm-driven credit assessment in business finance.
The agreement, signed on Thursday, integrates chamber members into Ansar Digital Financing, ZamZam Bank’s digital financing platform launched in December 2024 in partnership with Kifiya Financial Technology. The system will allow eligible businesses to access loans ranging from 60,000 birr to 1 million birr without conventional collateral.
Lending decisions will be determined through an artificial intelligence based credit scoring system intended to evaluate repayment capacity without conventional collateral requirements.
The platform has already disbursed more than 1.1 billion birr in unsecured loans to over 10,000 small and medium-sized enterprises, a significant share of which have gone to women-led businesses. Around 18,000 businesses are currently awaiting credit decisions through the system, highlighting both rising demand and the growing backlog in digitally processed SME lending.
Addis Ababa Chamber of Commerce and Sectorial Association said the initiative is designed to ease financing constraints that continue to weigh on small businesses, many of which remain outside the reach of traditional bank lending despite their role in employment creation and urban commerce.
ZamZam Bank chief executive Melika Bedre said the model is expected to widen financial inclusion by improving the efficiency and reach of lending to small and medium-sized firms, particularly those lacking formal collateral records.
The agreement reflects a broader, still uneven transition in Ethiopia’s banking sector, where lenders are increasingly experimenting with artificial intelligence and alternative data to assess creditworthiness. Digital lending platforms are being deployed to analyse transaction histories and behavioural data, gradually reducing reliance on physical assets as the primary gatekeeper for credit.
One prominent example is the Kifiya Financial Technology powered lending ecosystem, which has expanded uncollateralised lending to micro and small enterprises in partnership with commercial banks and micro finances. The model has become a reference point for the sector as banks test the boundaries of data-led finance.
Adoption, however, remains patchy. Larger and more technologically advanced lenders have moved first, while smaller institutions lag behind, constrained by infrastructure and data limitations. Regulators are watching closely as Ethiopia’s banking system attempts to balance broader credit access with concerns over model transparency, data governance and financial stability.




