

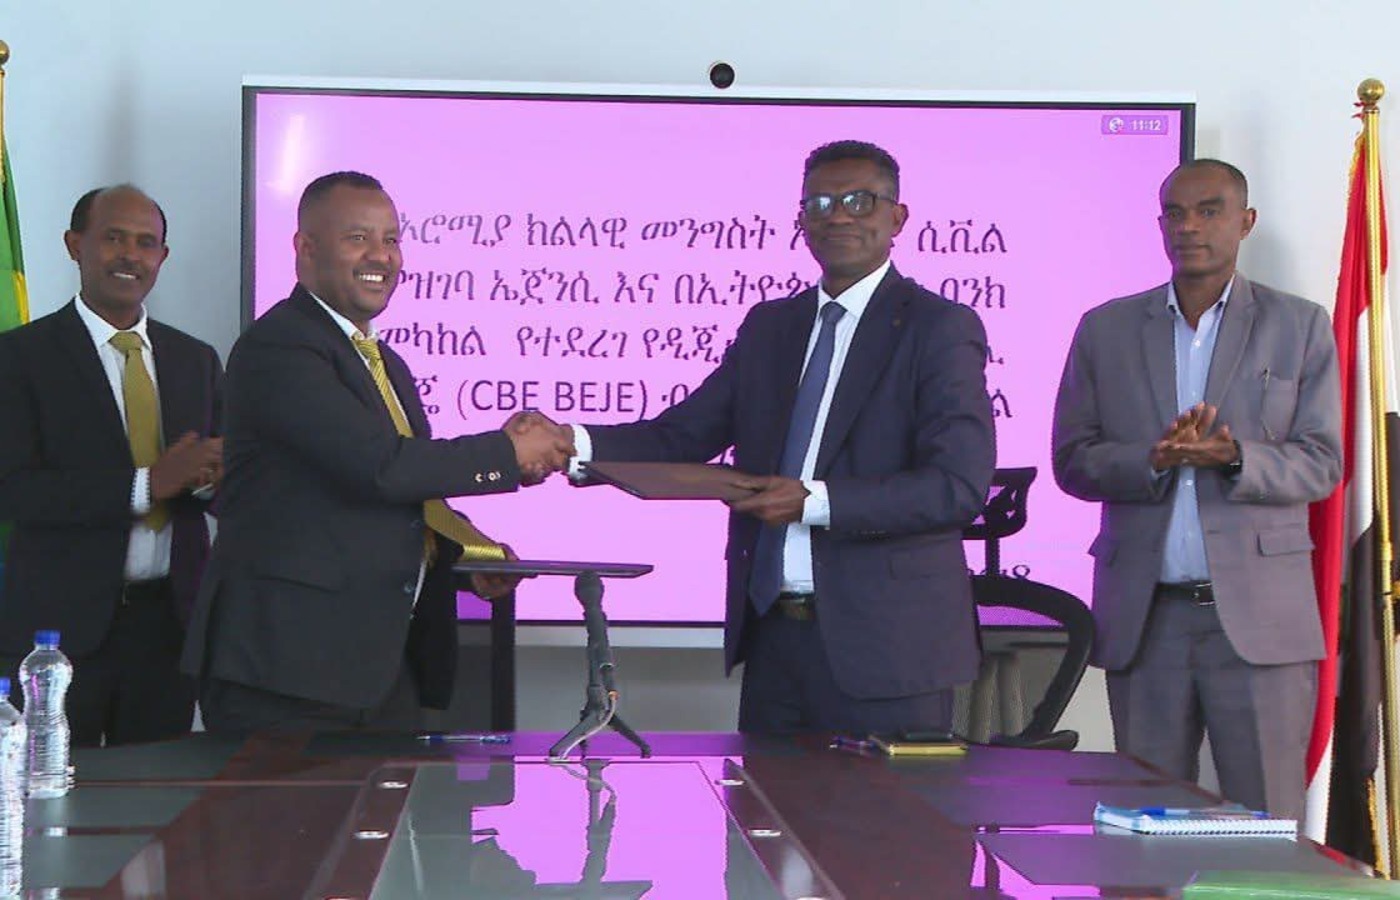
The Commercial Bank of Ethiopia (CBE) has signed an agreement with the Oromia Civil Registration Agency to provide its employees with collateral-free digital loans, extending the state-owned lender’s payroll-linked credit drive into Ethiopia’s largest regional state.
The memorandum of understanding was signed by Chala Gemechu, director of CBE’s Bole District, and Tessema Bekele, chief executive officer of the Oromia Civil Registration Agency.
Under the agreement, eligible agency employees whose salaries are processed through CBE will be able to borrow between 500 birr and 150,000 birr through the CBE Birr Plus mobile application.
Loan limits will be determined partly by an employee’s monthly salary, while repayment periods will range from one to 12 months. The service does not require borrowers to provide conventional physical collateral.
Chala said the agreement would enable employees of the agency to use CBE Beje, the bank’s digital savings and lending service for salaried workers. By linking loan eligibility to verified salary payments, CBE can assess borrowers and collect repayments through their accounts.
Tessema said the arrangement would provide agency employees with faster access to short-term financing through a digital platform.
The agreement covers employees of the Oromia Civil Registration Agency and does not automatically extend the service to all regional civil servants. However, it gives CBE an institutional entry point into Oromia’s large public-sector workforce as the bank seeks additional salary-transfer agreements with government bodies.
CBE formally launched CBE Beje in November 2025, offering collateral-free loans ranging from 500 birr to 150,000 birr to employees whose organisations have signed payroll-processing agreements with the bank.
At the time of the launch, CBE said 478 institutions had signed agreements to process salary payments through CBE Birr, although employees at 83 institutions had begun receiving loans. The bank reported disbursing more than 1.6 billion birr through the service during its initial two-month rollout.
CBE has since signed similar agreements with other public institutions. In February 2026, it reached an agreement with Ethiopian Electric Utility to provide CBE Beje services to more than 21,000 employees under the same lending range.
The bank’s institutional agreements combine credit expansion with deposit mobilisation. Organisations channel salaries through CBE, generating regular deposit inflows, while employees become eligible for loans assessed against their monthly earnings and transaction records.
The expansion of CBE Beje forms part of a wider shift in the bank’s consumer-lending strategy. In November 2025, CBE approved a new Consumer Loan Procedure for Retail Customers, establishing standard rules for mortgage and automobile loans offered to mass-market, middle-income and affluent customers.
Under the procedure, mortgage loans may be used to construct, purchase, renovate or expand residential properties. Borrowers are required to finance at least 50 percent of the property cost themselves. The framework also introduced standard eligibility, documentation, income and credit-history requirements.
CBE Beje operates separately from the mortgage and automobile loan framework, focusing instead on smaller, short-term loans issued digitally to salaried employees. Together, the products signal CBE’s attempt to expand its retail loan portfolio as domestic banks compete more aggressively for individual customers and institutional payroll accounts.
The expansion is also taking place following a major change in Ethiopia’s monetary policy. In July 2026, the National Bank of Ethiopia removed the annual credit-growth ceiling that had limited commercial banks’ lending expansion to 14 percent.
The central bank said the ceiling, introduced in 2024 to contain inflation, would be replaced by indirect instruments including the policy interest rate and reserve requirements. It also warned that additional reserve requirements could be imposed on banks whose lending growth contributes to inflationary pressure.
The removal of the cap gives CBE and other commercial banks greater flexibility to expand credit, including salary-backed retail lending, while remaining subject to the central bank’s broader monetary controls.




